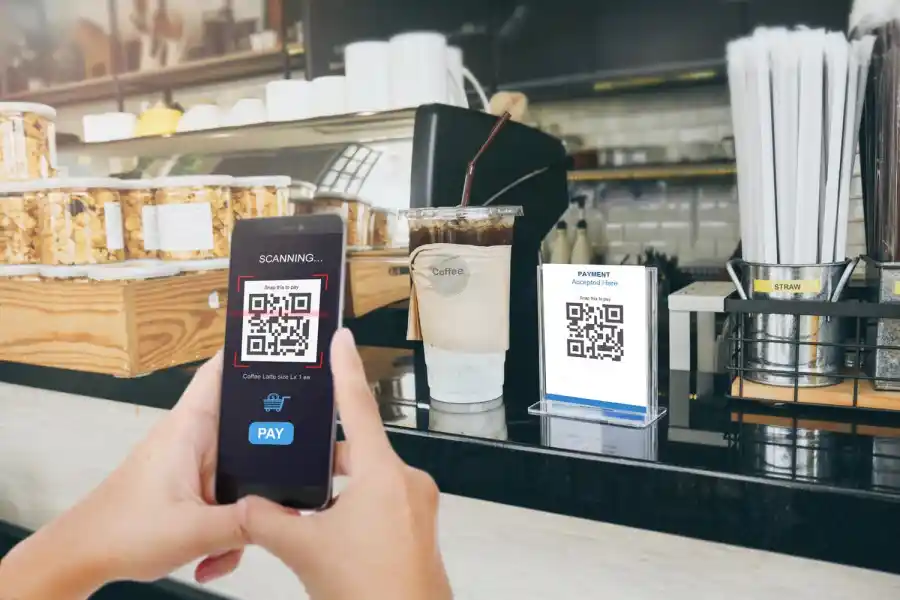
Competition between China and India is not confined to trade, investment, and geopolitical influence. It is also extending into digital payment systems, which are increasingly shaping the direction of the modern economy. For Nepal, a country situated between two Asian powers, these developments present opportunities to expand trade, improve transaction efficiency, and strengthen financial inclusion. However, these opportunities also carry risks: dependence on foreign payment systems could limit Nepal’s economic policy space if not managed properly.
The issue is not about choosing China’s or India’s payment system. Nepal’s challenge is to leverage the technology and networks of both countries to strengthen its domestic payment infrastructure, improve local business competitiveness, and capture greater economic benefits.
Geographically, Nepal borders India to the south, east, and west, and China to the north. As a landlocked country, Nepal depends on regional connectivity for trade and population mobility. Therefore, cross-border payment systems have strategic significance, particularly for tourism, border trade, and remittances.
India offers payment integration through the Unified Payments Interface (UPI), while China has a growing digital payment ecosystem through platforms such as Alipay and WeChat Pay. Both offer technological options that could help Nepal serve consumers and businesses connected to the two countries.
A concrete development occurred on June 6, 2026, when the link between India’s UPI and Nepal’s National Payments Interface began operating for cross-border person-to-person money transfers. The system enables real-time transfers through supported banks and digital wallets.
Meanwhile, payment cooperation through Alipay has already been established in Nepal. In its 2024 payment system oversight framework report, Nepal Rastra Bank recorded that in 2023, Alipay transactions processed through acquiring services reached NPR 40.3 million, with more than 24,000 merchant locations. These figures show that cross-border payments are not merely a future agenda, although the coverage and scale of each system differ.
Payment Infrastructure and the Challenge of Dependence
Nepal is not starting from scratch. Its domestic payment infrastructure has developed through the National Payment Switch and Retail Payment Switch. According to Nepal Clearing House, the Retail Payment Switch processed transactions worth more than NPR 1.2 trillion in the month of Ashadh 2083 and a total of NPR 9.3 trillion during fiscal year 2025/26.
This transaction volume demonstrates that Nepal has a foundation for developing a more integrated digital payment system. However, the next challenge is to expand interoperability with other countries without weakening the capabilities of the national system. In platform economics theory, the more users and merchants connected to a system, the greater the benefits generated by network effects. However, network effects can also create dependence when users and businesses find it difficult to switch platforms or face high costs when using alternative systems.
For Nepal, such dependence could emerge when tourism transactions, trade, or remittances increasingly rely on foreign infrastructure that is not entirely under the control of domestic regulators. Therefore, expanding connectivity must go hand in hand with data protection, cybersecurity, fee transparency, and dispute resolution mechanisms.
The Economic Benefits Nepal Should Pursue
First, cross-border payments can reduce transaction barriers for tourists and traders. Indian tourists can use familiar payment services, while integration with other payment systems could potentially facilitate transactions for Chinese tourists. The benefits will be felt by hotels, restaurants, small shops, and local businesses if transaction costs remain competitive and payment settlements proceed smoothly.
Second, digital systems can help improve remittance efficiency. Fast and transparent transfers make it easier for families to receive funds and reduce dependence on slow procedures. However, cost savings need to be demonstrated by comparing service fees, exchange rates, and intermediary charges before and after integration.
Third, digital payments can expand MSMEs’ access to the formal economy. Recorded transaction histories could help businesses build financial track records to access financing. Nevertheless, these benefits will not materialize automatically without consumer protection, financial literacy, and responsible credit policies.
The Asian Development Bank’s report on digital payments in Nepal, July 2026, emphasizes the importance of improving infrastructure, interoperability, adoption by small businesses, and skills development. In other words, success is not simply a matter of increasing the number of digital transactions, but also of enabling the system to expand productive economic activity.
Toward Digital Payment Autonomy
Through a strategic autonomy approach, Nepal needs to build the capacity to determine its own policy direction while remaining open to cooperation with external partners. Autonomy does not mean rejecting UPI, Alipay, or WeChat Pay, but ensuring that such integration strengthens national economic interests.
First, Nepal needs to maintain interoperable domestic payment infrastructure capable of connecting with various foreign networks through transparent standards. Second, regulators must establish requirements for security, data protection, fee transparency, and oversight of cross-border payment providers. Third, the expansion of payment systems must involve banks, financial technology companies, and local MSMEs so that value added is not enjoyed exclusively by foreign platforms.
Fourth, the government needs to measure success through reductions in transaction costs, increased adoption by MSMEs, growth in cross-border transactions, and more equitable access. Evaluations should also cover system resilience and Nepal’s ability to maintain service continuity if disruptions occur in foreign networks.
Thus, competition between China’s and India’s digital payment systems can provide Nepal with an opportunity to strengthen trade and financial inclusion. However, these benefits will only be sustainable if international connectivity is accompanied by strong domestic capabilities. The measure of Nepal’s success is not which country controls its digital payments, but how far these payment systems increase productivity, reduce economic costs, and strengthen Nepal’s control over its own financial infrastructure.