SCO, BRICS and the Pursuit of Strategic Autonomy
1. Introduction: The Puzzle of a Country That Refuses to Choose
In a world splitting into rival camps, India remains in all of them at once. It anchors the Quad with the United States, Japan and Australia, holds full membership in the Shanghai Cooperation Organisation alongside China and Russia, and helps run an expanded BRICS that now includes Iran, Egypt and the United Arab Emirates (Pandey and Yadav 2025; Bharti and Nepal 2025). Delhi buys discounted Russian crude while deepening defence cooperation with Washington, and it balances a trade surplus with the United States against a Chinese-dominated import basket (Bhagwat and Rogachev 2025; Gegeshidze and Baranec 2025; Shukla 2023). Two readings compete. The first sees defensive hedging, an insurance position between balancing and bandwagoning adopted by states that cannot choose (Vinodan and Kurian 2024; Tan and Soong 2022). The second, pursued here, sees an active connective strategy: overlapping engagement with every centre of power converted into bargaining space, commercial concessions and autonomy of decision (Kara 2025). The SCO and BRICS are the decisive cases.
2. What Is the Nalanda Approach?
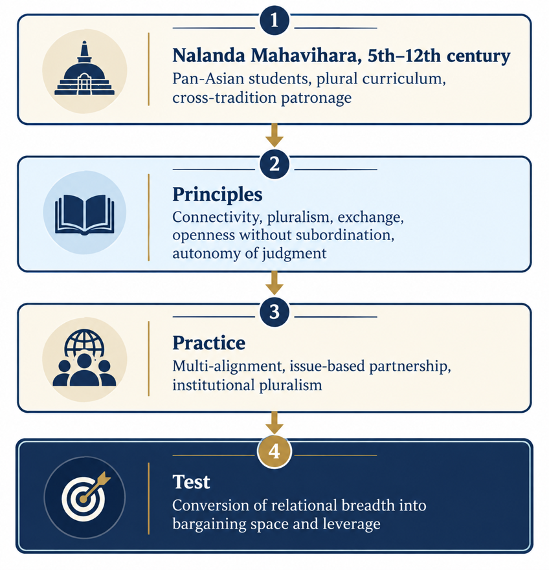
Between the fifth and twelfth centuries Nalanda drew students from Korea, Japan, China, Tibet, Indonesia, Persia and Turkey, taught astronomy, linguistics and medicine beside Buddhist philosophy, and was sustained by patronage from Hindu and Buddhist courts alike (Beck 2017; Pinkney 2014). Its revival, announced at the 2007 East Asia Summit, was framed explicitly as pan-Asian connection (Wu and Panthaki 2017; Pinkney 2014). The Nalanda Approach proposed here is an analytical construct, not a recovered doctrine; nothing suggests ancient Nalanda formulated foreign policy. Its relevant features translate into principles: connectivity as a standing posture, pluralism among partners, exchange without absorption, openness that stops short of dependence, and autonomy of judgment. Alliance theory asks which side a state chooses; the Nalanda Approach asks how much strategic space a state can hold by refusing the choice itself. It is a claim about converting relational breadth into power, and breadth can equally mean exposure, which is why the claim must be tested.
3. From Non-Alignment to Strategic Autonomy
The genealogy matters because the terms are not synonyms. Non-alignment was negative and ideological: India refused the blocs in a bipolar order. Strategic autonomy is positive and operative: India sets its own agenda and partners selectively, which is why it can sit in both BRICS and the US-led Indo-Pacific Economic Framework (Zomuanthanga and Shekhawat 2026). Multi-alignment describes the institutional expression, membership across Quad, SCO, BRICS and G20 as insurance (Vinodan and Kurian 2024). The Nalanda Approach names the connective intent: not declining to choose but engineering connection so that each partner’s need for India outbids India’s need for any partner (Meena 2025). The counter-reading deserves full weight. Scholars of hedging argue it is a passive response to uncertainty rather than an active choice, durable only while the uncertainty lasts (Tan and Soong 2022). If they are right, India’s breadth is contingent, not doctrinal. The distinction is testable: hedging preserves options, while connective strategy uses options to shape outcomes.
4. The SCO as Continental Expression
The SCO is the hardest case. India joined in 2017 alongside Pakistan, entering a body dominated by China and Russia; Iran followed in 2023 and Belarus in 2024 (Kenbayev and Parikh 2025). Measured as a security community the organisation fails: its members accept no binding commitments, and comparisons with the CSTO show integration that is protective in rhetoric and shallow in practice (Allison 2018). That is precisely its utility. Russia and China diverge on enough questions to leave room for a third player, so India can participate without absorption (Lanteigne 2017). It gains standing channels to Central Asia, where its connectivity ambitions are genuine (Meena 2025). And formal equality yields leverage: at the 2025 summit Delhi used the consensus rule to block Azerbaijan’s accession, an exclusion that drew red lines without confrontation (Kenbayev and Parikh 2025). Engagement does not require agreement. India treats the institution as a medium, not a commitment.
5. BRICS as Economic Multipolarity
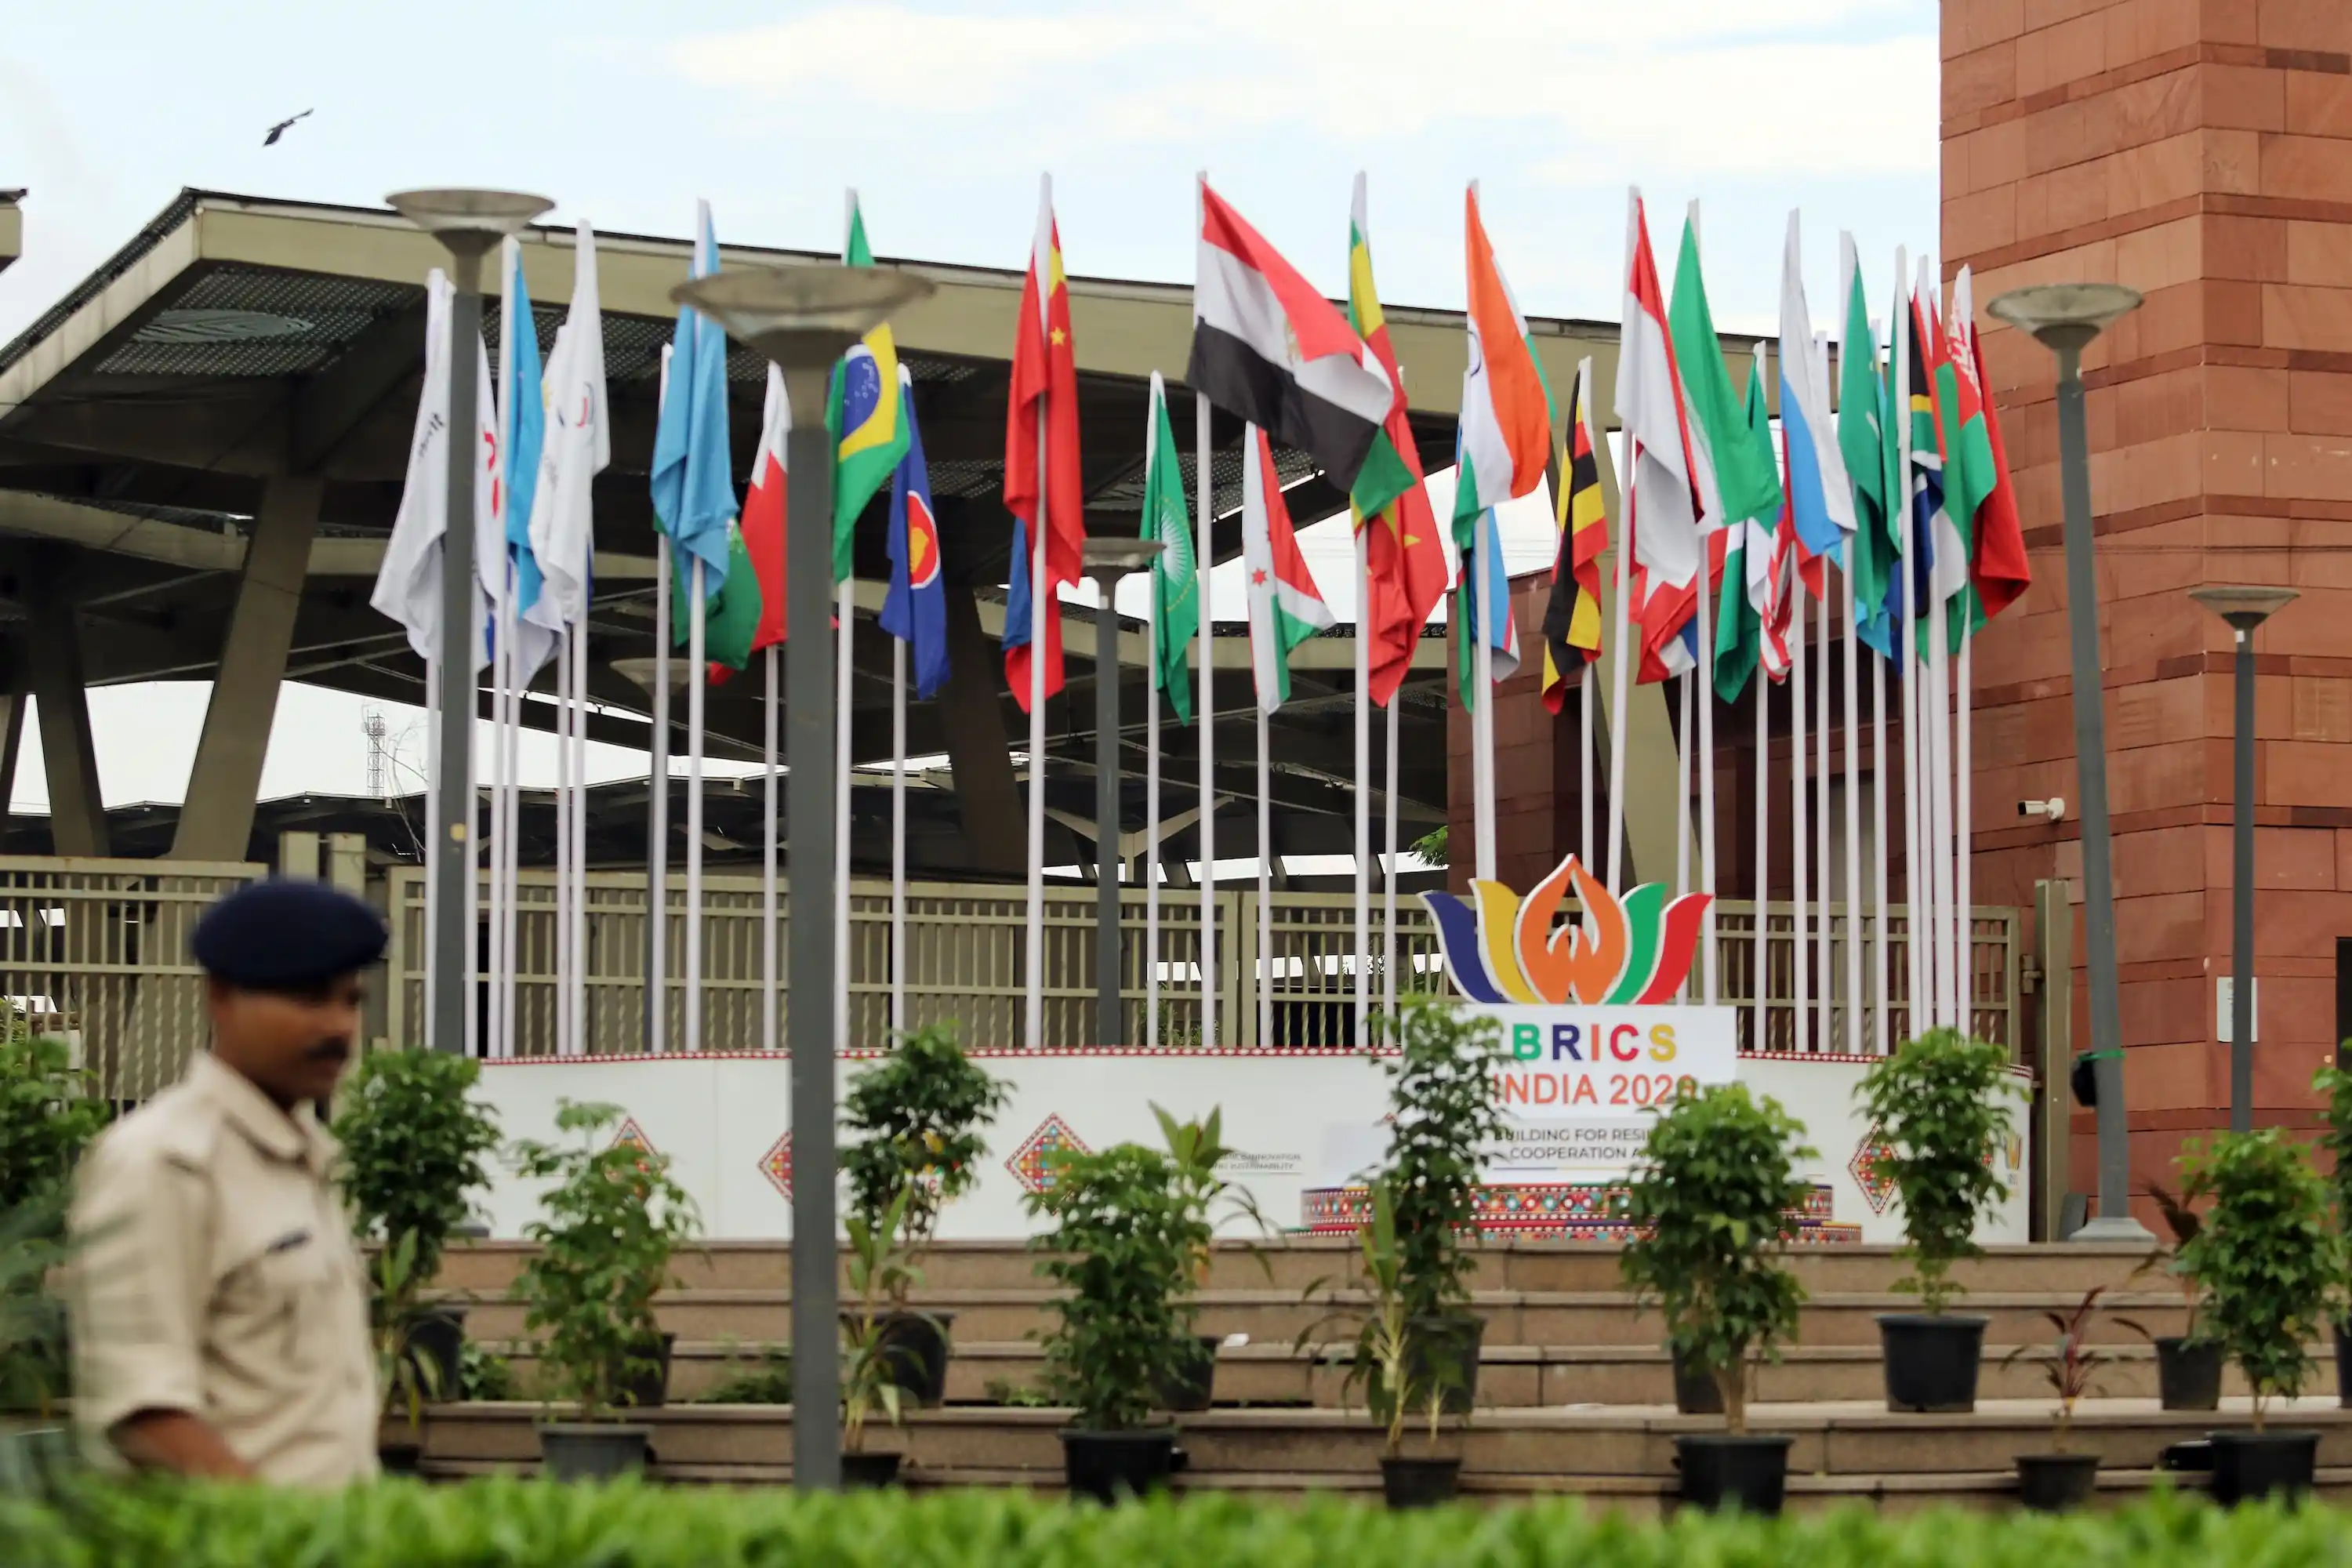
BRICS is the clearer test of whether connectivity shades into alignment. Egypt, Ethiopia, Iran and the UAE joined in January 2024, thirteen states were named partners, and the enlarged group claims roughly 45 percent of the world’s population; Argentina, invited at Johannesburg, withdrew (Lissovolik 2023; Burakowski 2025). India’s ambivalence about expansion is itself evidence: Delhi does not want the platform to harden into a Beijing-led caucus, treats de-dollarisation with studied caution, and keeps balancing BRICS against Western economic fora (Zomuanthanga and Shekhawat 2026). Western media read the group as a challenge to the liberal order; Indian reporting reads it as developmental pluralism (Bharti and Nepal 2025). The scholarly verdict splits the difference: BRICS is an instrument for expanding bargaining space, one of a plethora of ad hoc arrangements India uses rather than belongs to (Burakowski 2025). The yuan question remains the point at which the platform could become a trap.
| Dimension | SCO | BRICS |
| India’s membership | 2017, alongside Pakistan; Iran 2023; Belarus 2024 | Founding member; enlarged January 2024 by Egypt, Ethiopia, Iran, UAE; 13 partner states |
| Principal value | Eurasian and Central Asian connectivity; rule-setting via consensus | Global South platform; bargaining space relative to Western institutions |
| Points of friction | China-Russia preponderance; India-Pakistan rivalry | Risk of a Beijing-led, anti-Western caucus; yuan reserve role and de-dollarisation |
| Nalanda test | Engagement without agreement | Plural membership without absorption |
6. India as Connector
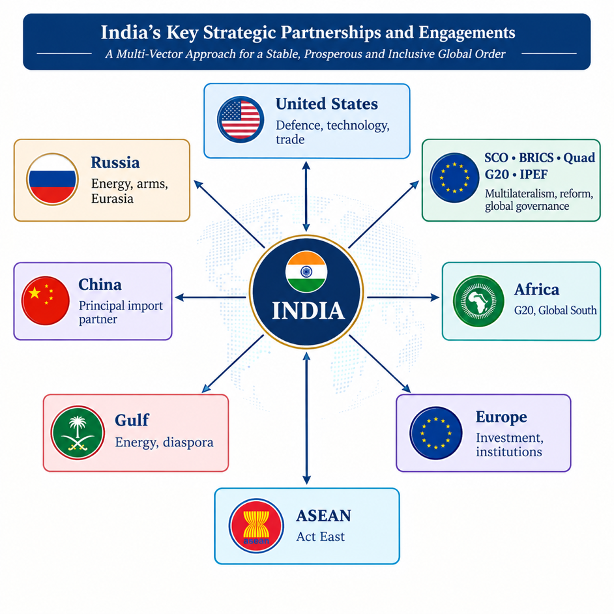
The portfolio logic extends to bilateral relations: defence and technology with the United States, energy and equipment with Russia, remittances in the Gulf, markets across ASEAN, Europe and Africa (Wezeman et al. 2024). Under India’s G20 presidency the African Union joined the grouping permanently and the Voice of the Global South summits convened (Hossain and Howard 2025; Kumar 2025). Each relationship is deep, none exclusive; the portfolio is the anchor. The comparison with Australia is instructive: Canberra’s hedging is anchored in alliance loyalty and institutional obligation, while India’s remains autonomy-preserving, closer to selective engagement than to commitment (Li 2025).
7. The Political Economy of Connection
Energy is the flagship and the warning. India imports 85 percent of its petroleum needs, and Russia’s share of its oil imports rose from 1 percent in February 2022 to 21 percent by September of that year, on track to surpass Iraq and Saudi Arabia combined by April 2023 (Ravikumar and Downey 2024; Kulik 2023). The shift saved India roughly $5 billion on its 2022 import bill and cut Gulf suppliers’ share to about 42 percent in mid-2023 (Sim 2024). Scholars describe the policy accurately as strategic arbitrage, multi-vector sourcing across Russia, the United States, Iraq, Saudi Arabia and Africa that buys competitiveness and distance from the sanctions coalition (Korchak 2026). The mirror image is the import dependence on Chinese manufacturing that diversification has not touched, and exposure to US pressure including tariffs on Russian oil (Verma and Rizvi 2025; Bhagwat and Rogachev 2025). Energy has long been the hinge of India’s relations with both Moscow and the Gulf (Rout and Sethy 2023). Connectivity multiplies leverage in both directions; the approach is only as strong as India’s least diversified dependence.
8. Three Currencies of Power: A Comparative Assessment
Comparative assessment sharpens when disaggregated into the three currencies through which states convert capability into influence: economic weight, military capacity, and the soft power to attract rather than coerce (Nye 2004). By the first two measures the disparities are stark. The United States spent an estimated $997 billion on defence in 2024, more than the next nine countries combined, atop a nominal GDP of roughly $30.5 trillion (SIPRI 2025; International Monetary Fund 2025). China’s $314 billion in military spending and $19.2 trillion economy make it the only state approaching American scale on both counts. Russia’s economy, at roughly $2.2 trillion, is smaller than India’s, even though its $149 billion military budget, inflated by the war in Ukraine, still exceeds India’s $86.1 billion. India ranks fifth in military spending and fourth or fifth in nominal GDP depending on the reporting period, comfortably behind both the United States and China on either hard metric (SIPRI 2025; International Monetary Fund 2025).
The soft power register complicates rather than confirms this hierarchy. The 2025 Global Soft Power Index ranks the United States first and China second, their economic and military weight reinforced by cultural and diplomatic reach; Russia, its reputation damaged by the war in Ukraine but still buoyed by support among Eastern partners, sits sixteenth; India ranks twenty-ninth, ahead of Russia in absolute score only marginally but on a fraction of Russia’s military budget, and far behind China (Brand Finance 2025). No single currency orders the four powers identically. China leads on two of three measures and is closing on the third. Russia over-performs militarily relative to its economy and under-performs on reputation relative to its history. India under-performs on the first two measures and roughly matches Russia on the third despite spending less than a fifth as much on defence. The mechanisms differ as much as the totals: Washington converts economic and military primacy into hierarchy through formal alliances, Beijing converts economic weight into access through infrastructure and lending, and Moscow converts a comparatively small economy into outsized influence by fusing energy, arms and diplomacy into single-dependency relationships (Li 2025; Kara 2025). India, lacking comparable leverage in any one currency, relies instead on the breadth of overlapping partnerships to compensate.
| Currency of power | United States | China | Russia | India |
| Military expenditure, 2024 (US$ billion) | 997 | 314 | 149 | 86.1 |
| Nominal GDP, 2025 (US$ trillion, approx.) | 30.5 | 19.2 | 2.2 | 4.2 |
| Global Soft Power Index 2025 (rank / score of 100) | 1st / 79.5 | 2nd / 72.8 | 16th / 58.1 | 29th / 49.8 |
| Leading currency of power | All three | Economic and military | Military relative to economy | None decisively; distributed across all three |
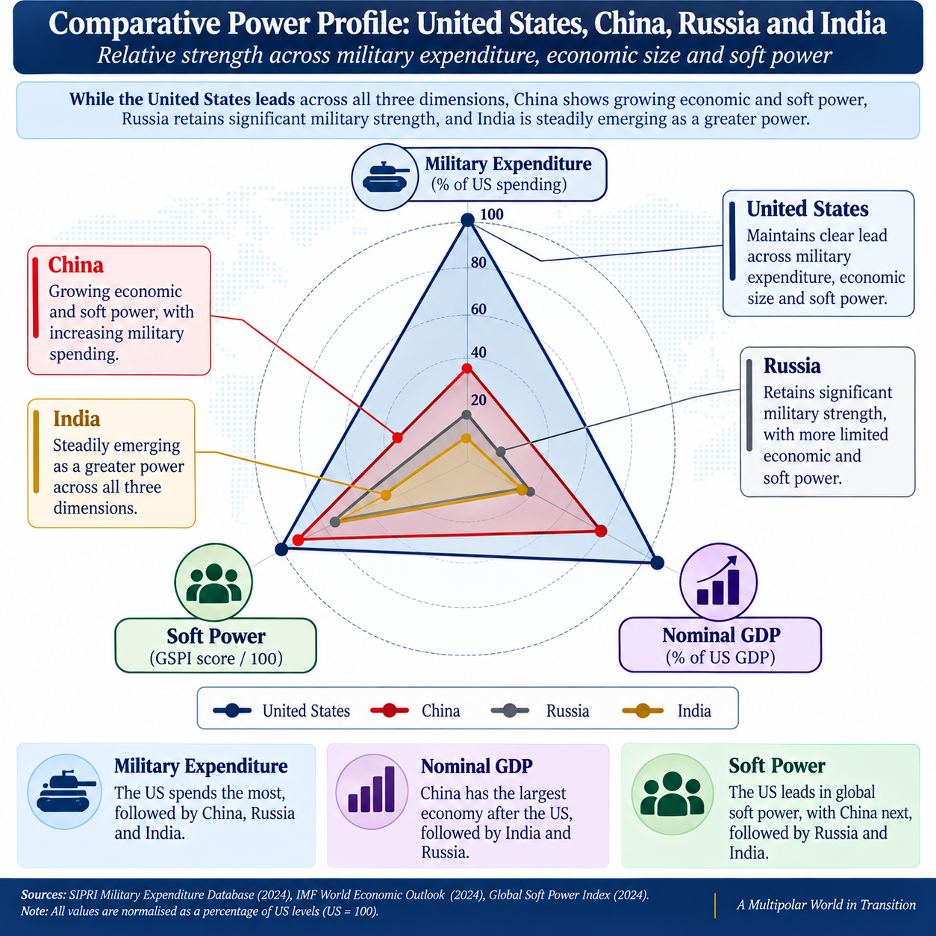
This is precisely the terrain the Nalanda Approach is built for. Rather than compete on any single currency, where India trails at least one great power on every measure, the strategy treats convertibility itself as the asset: diplomatic voice earned through SCO and BRICS membership offsets economic weight India does not have; a soft power ranking still modest in absolute terms but comparatively resilient to sanction and reputational shock sustains relationships that hard power alone could not; and selective military and economic partnerships, Russian arms, American technology, Gulf energy, avoid concentrating dependence in any single register. Smart power, in Nye’s later formulation, describes the deliberate combination of hard and soft instruments by a single actor (Nye 2011). The Nalanda Approach is better described as portfolio power: the attempt to remain solvent in every currency simultaneously, so that relative weakness in one need not become an absolute strategic vulnerability. Whether that portfolio can be sustained if any single currency collapses, a defence budget permanently outpaced, a further reputational shock, is the question the empirical probe below examines.
9. An Empirical Probe
A formal concentration index requires supplier-level shares across all markets, not compiled here; the directional evidence is nonetheless pointed. Russia’s share of India’s arms imports fell from 64 percent in 2013-17 to 45 percent in 2018-22, with new orders spreading to Western suppliers (Wezeman et al. 2023, 2024). In energy the direction reversed: from 1 percent of oil imports in February 2022 to 21 percent by September 2022 and continued growth thereafter (Ravikumar and Downey 2024; Kulik 2023). In trade, the United States displaced China as India’s largest partner in 2022-23 at $128.55 billion, before China returned to roughly $118.4 billion in 2023-24 (Sharma and Sharma 2025). Export intensity toward China fell from 1.10 in 2005 to 0.33 in 2023, while import intensity held at 1.21 (Verma and Rizvi 2025). Diversification is genuine in defence and exports, sticky in imports and reversed in energy. The approach is vindicated where India controls the switch, exposed where it does not.
10. Conclusion
The puzzle resolves only partially. India’s refusal to choose is becoming a connective strategy with measurable payoffs, from cheap energy to institutional voice and a rising cost of coercion against it. But the energy record shows connectivity can concentrate risk, and the hedging literature reminds us that options held under uncertainty are not doctrine (Tan and Soong 2022). As an analytical framework, the Nalanda Approach nonetheless earns its place: it captures what non-alignment no longer does, an active and value-generating engagement with every centre of power. In a fragmenting international order, the ability to connect competing worlds can itself become a form of strategic power.