How does a country bargain with partners that have already cut their tariffs to zero? That was India’s problem with the European Free Trade Association (EFTA): Iceland, Liechtenstein, Norway, and Switzerland. Switzerland, by far the bloc’s largest economy, abolished all industrial tariffs on January 1, 2024. A conventional deal therefore offered India little in return for opening its own market.
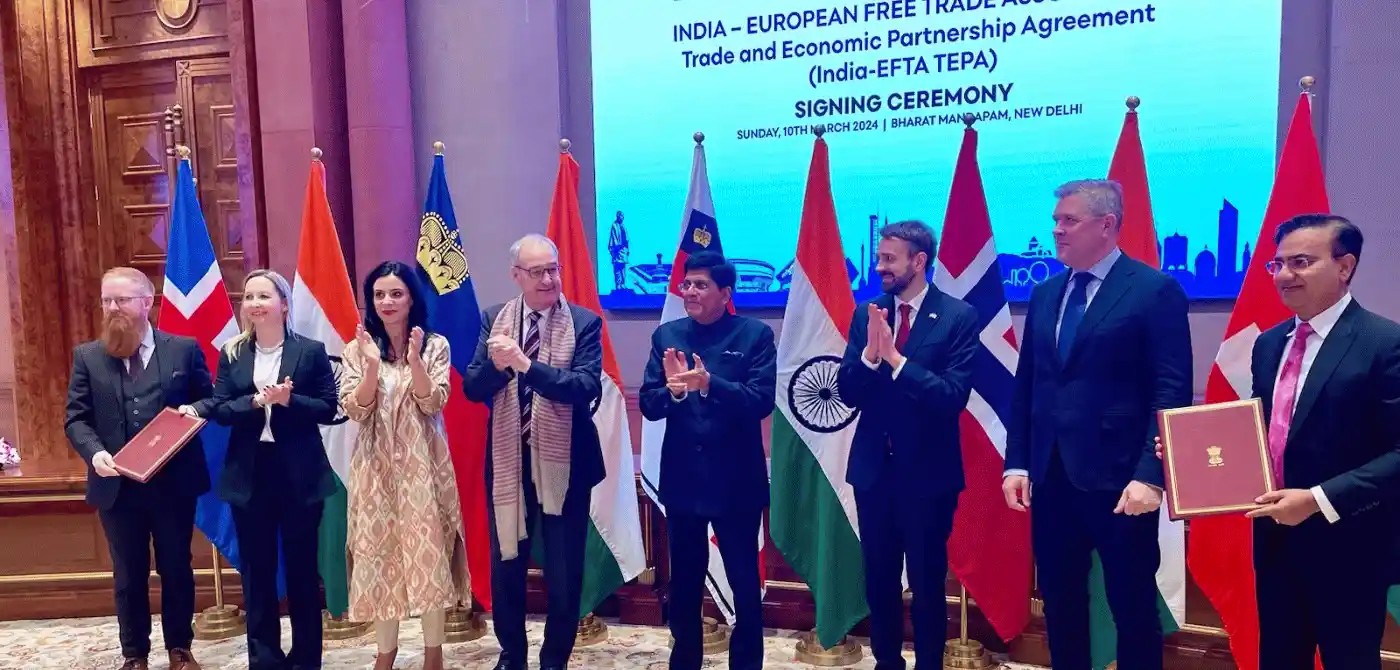
India’s answer was the India-EFTA Trade and Economic Partnership Agreement (TEPA), which trades tariff concessions for a promise of investment. It completed its first year in force on October 1. The question is whether this new kind of deal will actually bring investment, and whether other countries can copy it.
The imbalance India faced was stark. In 2024-25, it exported just $1.97 billion of goods to EFTA while importing $22.44 billion. Nearly all of the imports came from Switzerland, and most of them were gold. A tariff-for-tariff deal risked repeating India’s experience with ASEAN. In December 2019, Commerce Minister Piyush Goyal told the Rajya Sabha that India’s deficit with ASEAN had grown more than fourfold under their free trade agreement, from $5 billion in 2010-11 to $21.8 billion in 2018-19.
So New Delhi asked for capital. Under TEPA, the EFTA states “shall aim to” raise foreign direct investment in India by $50 billion within 10 years and by another $50 billion over the following five. They will also seek to facilitate one million direct jobs.
In return, India opened 82.7 percent of its tariff lines, covering 95.3 percent of EFTA’s exports, and agreed to phase out duties on goods such as Swiss watches and chocolates. Gold makes up more than 80 percent of those exports, and its effective duty did not change. Access to India’s market is a currency India has long spent cheaply. TEPA is the first time it has set a price at all.
The agreement breaks new ground. It is the first Indian trade deal to carry such a pledge. James Nedumpara and Pushkar Reddy, who assisted the negotiation of the investment chapter, called it a watershed in a paper for Columbia University’s Center on Sustainable Investment. They also saw it as a precedent for future agreements between developed and developing countries.
More significantly, it inverts the logic of investment treaties. Conventional treaties protect foreign investors, often by allowing them to sue host governments through international arbitration. TEPA’s investment chapter contains neither investor protections nor investor-state arbitration. This is a notable shift for a country that adopted a defensive model bilateral investment treaty in 2015, amid arbitration claims that included those brought by Vodafone and Cairn Energy.
The counting rules are carefully drawn. Article 7.1 of TEPA states that Foreign portfolio investment is excluded and sovereign wealth funds are exempt. Only investment by EFTA investors counts, not money that third-country firms route through EFTA.
One year in, the evidence is thin. The government has published no figure for EFTA investment under TEPA. On the anniversary, Goyal marked the date with a social media post restating the $100 billion pledge and the million-jobs target, without saying how much investment had arrived or how many jobs had been created. The signals that exist are anecdotal. In January, Switzerland Global Enterprise, the Swiss export promotion agency, said that the number of Swiss firms seeking support to enter the Indian market had more than doubled since the deal was signed. An India-EFTA Desk run by Invest India has been helping such firms since February 2025.
TEPA’s weaknesses are real. EFTA governments promise only to strive toward the target, and they cannot tell firms like Nestlé or Roche where to invest. The investment chapter is also excluded from the agreement’s state-to-state dispute settlement. The pledge is conditional, too. A footnote ties it to India sustaining nominal GDP growth of about 9.5 percent a year in dollar terms for 15 years. If India falls short, EFTA has a ready explanation for missing the target.
The penalty is also distant. India can seek consultations only if the targets remain unmet after 15 years. Talks then pass through three tiers: an investment sub-committee, the joint committee, and ministers. After the ministerial round, EFTA can request a three-year grace period. Remedies are unlikely before the mid-2040s. A deterrent that cannot be used for two decades exerts little pressure today.
Whether this model of Investment-linked trade can travel is also less clear. New Zealand’s agreement with India, signed on April 27, includes a $20 billion investment commitment over 15 years. The pledge works out to about $1.3 billion a year, roughly equal to the two countries’ entire goods trade in 2024-25. So, it seems that smaller economies are betting on India’s future market rather than its present one.
Larger partners have declined to follow. The U.K. agreement signed in July 2025 has no investment chapter, and the EU deal concluded in January 2026 sets no investment target. With the United States, the bargain ran the other way: under the February 2026 interim framework, India said it intends to buy $500 billion of American goods over five years. Against large partners, India’s leverage is weaker and the cost of walking away is higher, so New Delhi was right not to jeopardize those deals over a single clause.
The lesson extends beyond India. Many developing countries sign trade deals with advanced economies and end up importing more without building industrial capacity. TEPA offers an alternative bargain: market access in exchange for investment and jobs. Large emerging markets such as Indonesia, Vietnam, or Nigeria could pursue it with smaller, capital-rich partners. But such commitments have to be demanded; they are not offered. EFTA’s 2025 agreements with Malaysia and Mercosur contain no comparable target, even though Mercosur is a market of more than 270 million people.
None of this makes TEPA a gimmick. India turned a weak hand into a promise of factories and jobs. But the agreement should be judged on outcomes, not design. India should publish annual figures on EFTA investment measured against TEPA’s own counting rules. And If investment accelerates, India will have offered the Global South a workable template. If it does not, it will be left with a clever clause and a long wait.